Money has always been easier to understand when you can see it. For generations, children picked up the basics simply by watching adults pay for things, and the lesson that spending means giving something up came almost on its own.
That kind of learning is harder to come by now. Most payments happen in a second, with no visible exchange and nothing left behind to count. Parents still hope to raise kids who save, spend with care and avoid debt they can't manage. The difference is that those lessons no longer teach themselves, so families have to teach them on purpose.
What Changed When Money Went Digital
Before choosing how to teach, it helps to understand why digital payments confuse children in the first place. The problem isn't that kids are careless. It's that the signals they once relied on have quietly disappeared.
Spending Without Feeling It
Think about what a young child sees at a checkout today. A parent holds up a phone, the reader chimes, and the family leaves with their bags. Nothing seems to have been handed over. From where the child stands, the shopping was free.
Adults feel a small pinch when they pay, even by card, because they know their balance just went down. Children haven't made that connection yet. Without it, buying things can seem effortless, and that impression often lasts longer than parents expect.
Numbers That Don't Mean Much Yet
Young minds work best with things they can touch. A pile of coins makes sense. A figure on a screen does not. Even kids who can read "$40" correctly may have no feel for how long it takes to earn that amount or what else it could have bought.
This is why so many children seem to understand money in principle while acting as if it never runs out. The answer is to match the lesson to the child's stage of development, starting with the concrete and moving toward the abstract.
Lessons That Fit Each Stage of Childhood
Kids are ready for different ideas at different ages. The Consumer Financial Protection Bureau's Money as You Grow guide lays out age-based milestones that make a useful roadmap, and the stages below follow a similar path.
Ages 3 to 6: Making Money Real
At this age, the main goal is simple. Children need to learn that money is traded for things and that once it's spent, it's gone.
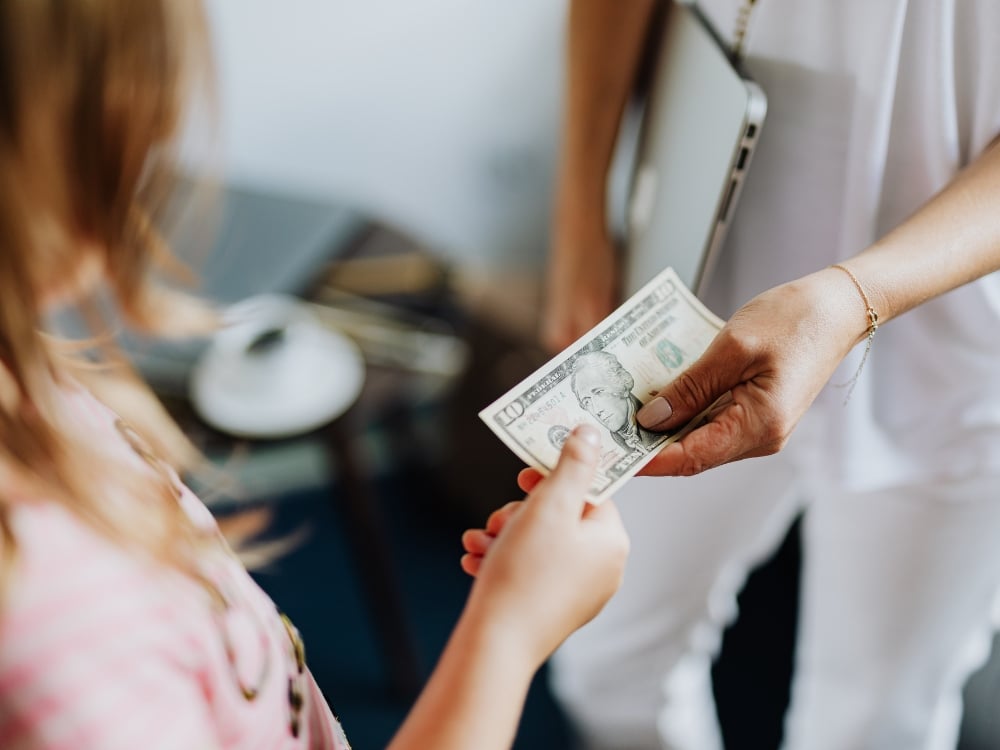
Cash is the best teacher here. Let your child hand coins to a cashier, or set up a pretend shop at home with real change. Clear jars labeled "spend," "save" and "share" work well too, because kids can watch each one fill up and empty out. Seeing the save jar grow slowly toward a goal gives patience a shape they can recognize.
Ages 7 to 12: Choices and Trade-Offs
Older children can handle a bigger idea: every purchase means not buying something else. A regular allowance, even a small one, gives them room to practice.
This is also a good time to make your own spending visible. Explain your choices out loud. "I'm paying for this with my card, and it comes out of the money I earned this month." Or, "We're cooking at home tonight because we're saving for our trip." Comments like these show kids that a card draws from a limited supply, just like a wallet does.
Games and apps deserve attention at this stage as well. Many sell virtual currencies such as gems or coins, which make the real cost hard to judge. Sit down together and work out what those purchases cost in dollars, then compare the total to something your child already values. That one conversation often changes how they view in-game spending.
The Teen Years: Practicing With Real Stakes
Teenagers shop online, split costs with friends and pay through apps. Keeping them away from digital money only delays the learning, so this is the time to hand over some control.
Debit and prepaid cards designed for teens let parents set spending limits and receive alerts for each purchase. That gives kids real practice with a safety net in place. A teen who spends a month's budget in the first week learns a lesson that sticks, and the price of that lesson stays small.
Encourage them to check their balance regularly and keep a simple record of what they spend. A notes app or a paper notebook works fine. The habit of noticing matters more than the method.
Why Good Financial Guidance Matters for the Whole Family
Teaching kids about money assumes parents feel confident about it themselves. Many don't, and that's nothing to be embarrassed about. Plenty of adults grew up without anyone explaining budgets, interest or saving, and it's hard to pass on knowledge you were never given.
Parents Need a Plan, Too
Children learn far more from what parents do than from what they say. A household with clear goals, such as an emergency fund, a debt payoff schedule or savings for college, naturally models steady and thoughtful habits. Good financial advice helps parents set those goals and stick to them, which makes everything they teach at home more believable.
Free, trustworthy resources are a sensible starting point. The federal government's MyMoney.gov site gathers plain-language guidance on saving, borrowing and protecting money, and it's useful for parents and older teens alike.
How AI Makes Advice Easier to Reach
For a long time, personalized advice meant hiring a financial advisor, which put it out of reach for many families. That's starting to change. Parents can now turn to AI-driven financial planning to explore savings targets, compare options and get answers to everyday questions whenever they come up. Someone wondering how much to set aside each month for a goal ten years away can get a clear starting point in a few minutes.
These tools can also become part of a child's education. A teenager sitting beside a parent can see how small changes in spending shift a long-term plan, which makes ideas like compound growth feel much less abstract. AI works best as a guide rather than a final authority, though. Parents should still weigh its suggestions against their own judgment and reliable sources.
Habits Worth Keeping as Payments Change
Payment methods will keep evolving, and today's apps may look outdated in a decade. That's why the most valuable lessons focus on decisions rather than devices.
Teach the Pause
Show kids how to stop for a moment before buying something. Do I need this? Can I pay for it without dipping into my savings? Will I still want it next week? These questions work just as well at a store counter as they do on a phone, and they'll keep working with whatever comes next.
Let Small Mistakes Happen
A child who regrets a $15 purchase has learned something valuable at a very low cost. An adult who makes the same mistake with a credit card pays much more. Give kids room to get things wrong while the stakes are small, and talk through what happened without turning it into a lecture.
Keep Money Talk Ordinary
Money conversations work best when they're short and frequent rather than rare and serious. Mention prices at the store. Explain why you picked one product over another. Share a goal you're saving toward. Children who hear about money often tend to see it as something normal and manageable, not something stressful or mysterious.
Conclusion
Digital payments have changed how children first experience money, but they haven't changed what kids need to learn. Children still need to understand that money is limited, that every choice has a cost and that patience pays off. By making money visible early, matching lessons to each stage of growth, getting sound guidance for themselves and keeping the conversation going, parents can give their kids a strong foundation. However money moves in the years ahead, those habits will still hold.
This is a collaborative post. All views and texts are our own.